What is Earned Wage Access? A Plain English Guide
 Mallika Mitra
|
September 18, 2026
When you’re waiting for a paycheck to hit your bank account, a few days can feel like weeks if you’re stressed about paying your bills. But earned wage access can help you bridge the gap by giving you access to your money a little early.
What is earned wage access?
Earned wage access (EWA) is a service that allows employees to access some or all of their paychecks ahead of their actual payday. Also sometimes called demand pay, daily pay, instant pay, same-day pay, instant payroll or accrued wage access, EWA can be offered by an employer as a workplace benefit or direct-to-consumer via a third-party service.
How does earned wage access work?
The exact timing of when you can access your money and how much you can tap into early will vary based on the program. For example, if you’re typically paid once or twice a week, EWA may allow you to access a portion in the middle of your typical payday cycle. Then, you’ll get the rest of the paycheck according to the normal schedule.
Here is a general step-by-step guide on how earned wage access works:
You earn wages: First, you must work to accumulate your wages. Remember that with EWA, the money is an advance on your upcoming payroll. You’re accessing money you’ve already earned, just outside of the typical payroll cycle.
Your balance becomes available: Depending on whether you’re using an employer-sponsored service or a direct-to-consumer one, your potential earnings for EWA will be determined by your payroll records or earnings history. You may need to download an app related to your service to see your balance and how much money you can access, which may vary per provider, or based on your payroll activity at any time.
You request the money: You ask to access either some or all of the money you’ve earned. You may have to agree to the terms on the platform, such as fees, and you will only be able to access up to a certain amount of your upcoming payroll, which may vary.
You receive the money: You’ll have to identify how you’d like to receive the funds, or if you want the money instantly (which may come with a fee) or access if fee-free in a few business days, depending on the provider.
You get the rest come payday: If you haven’t received your whole paycheck via EWA, the rest will come on your scheduled payday as usual. The amount you've advanced will be deducted from your next paycheck as repayment, so expect a smaller paycheck amount than usual.
Employer-based vs. direct-to-consumer EWA
Employer-based EWA is a business-to-business-to-consumer (B2B2C) service and entails your employer contracting with an EWA provider. The provider will typically integrate directly with your employer’s payroll system and schedule, and you’re offered the service as a company perk. Companies that offer EWA tend to have employees that are paid hourly. EWA providers determine your earned wages using your payroll records.
If your employer doesn’t offer this service, you typically can’t sign up. But there may be another way to access EWA: direct-to-consumer services, such as through Current’s Paycheck Advance service. These third-party platforms take your employer out of the equation; you sign up directly with the EWA company. Because your payroll isn’t directly integrated, the companies tends to use another method — such as your recurring payroll deposits (amount, length of time you’ve received them, etc) — to determine how much of your wages you may access in advance.
How much does earned wage access cost?
Whether the service is free or comes at a cost depends on your provider and how soon you need the money. If you’re getting EWA through your employer, the service is likely free, though you may need to pay for an expedited payment if you need the money sooner than within a few business days.
For direct-to-consumer services, the fees can vary widely. There may be a subscription fee or, similar to the employer-based services, a fee for instant arrival of your money. Some are available entirely for free if you wait a few business days to receive the funds.
Earned Wage Access FAQs
How soon will you receive the money?
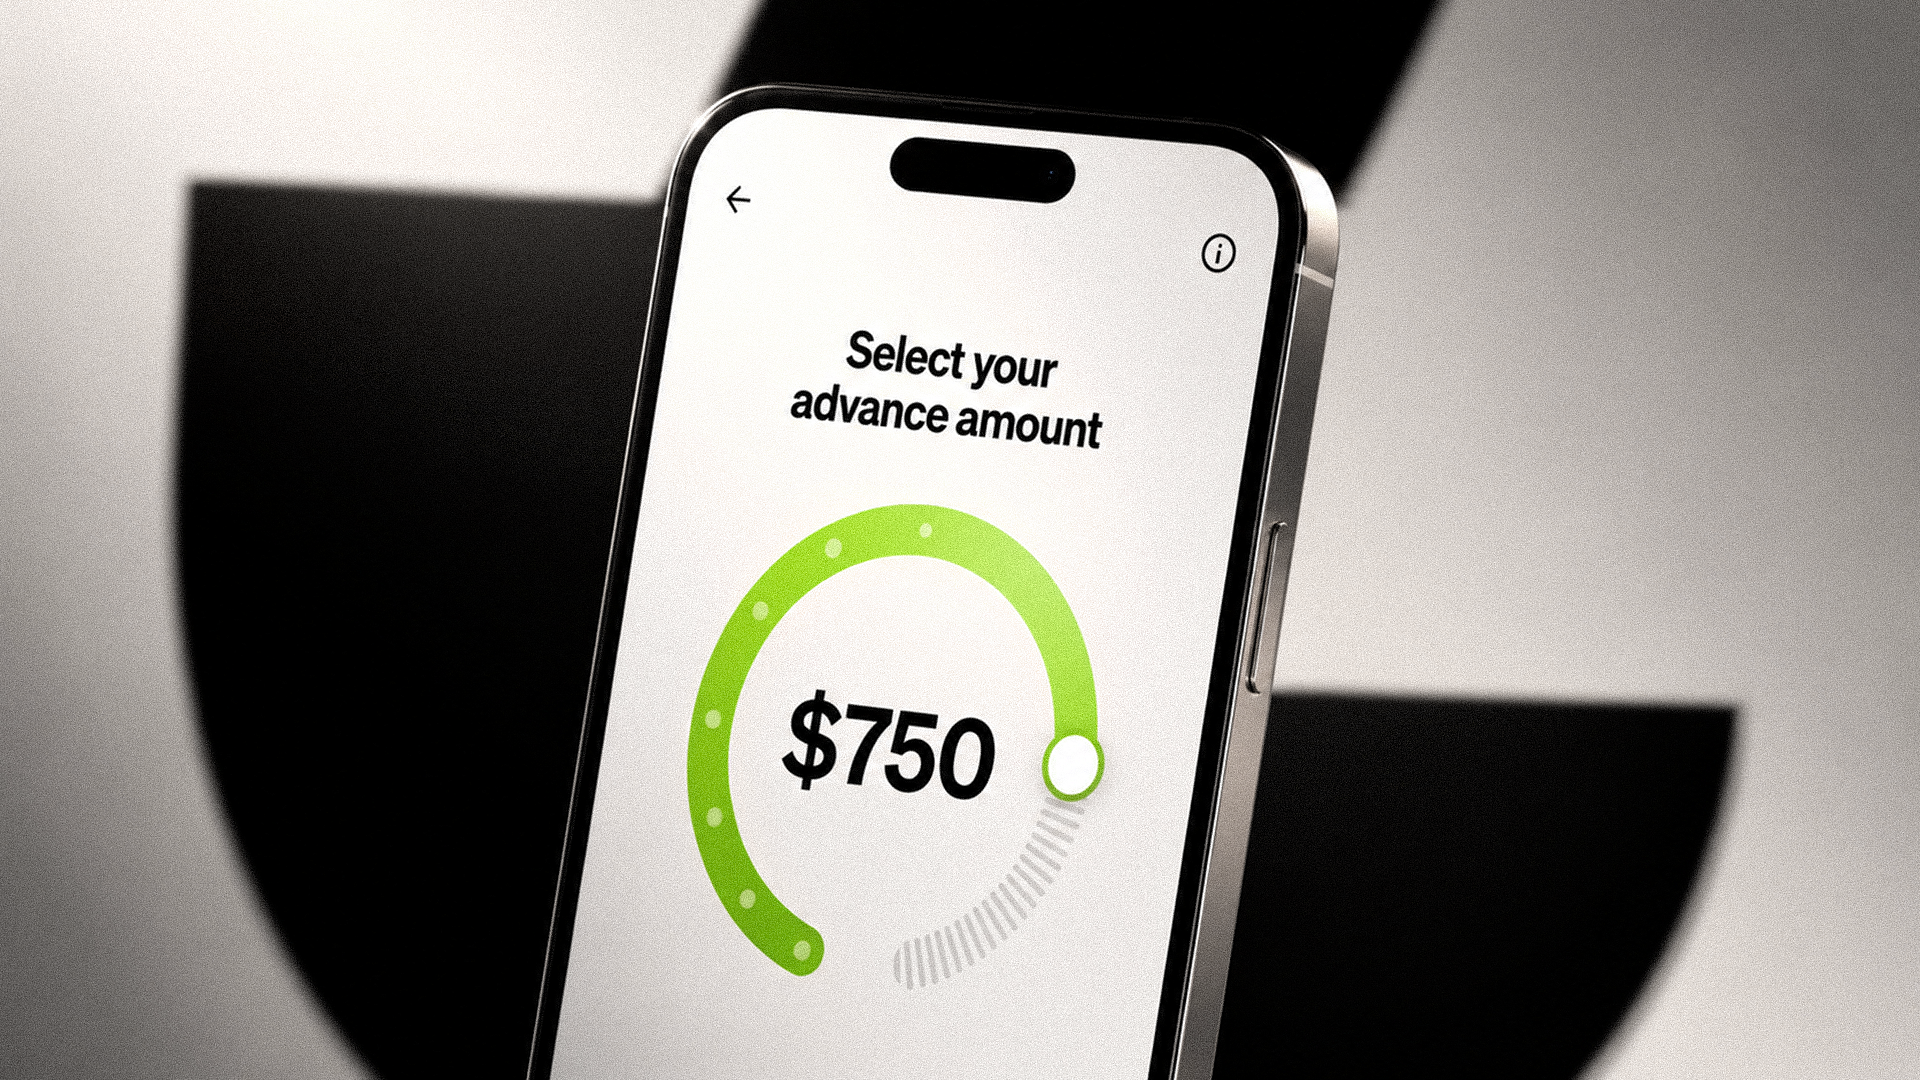
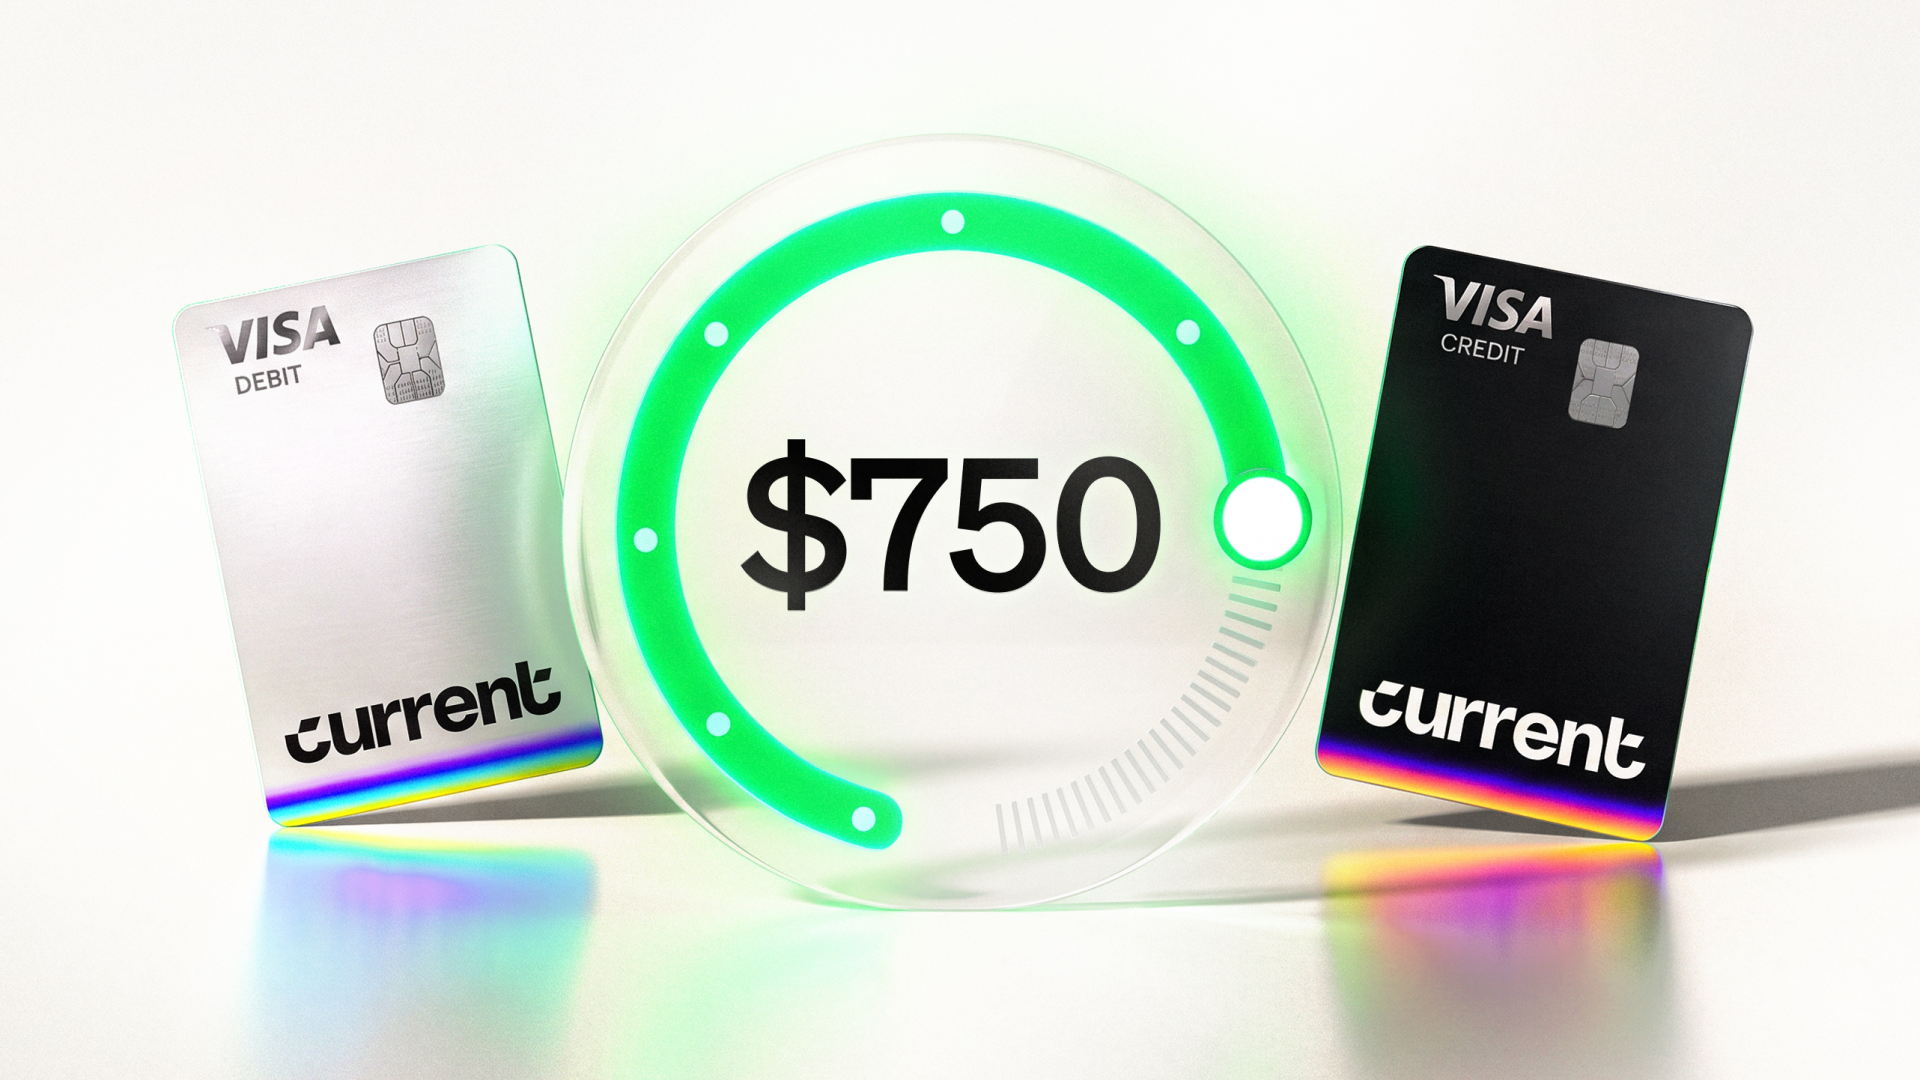
It typically takes a few business days to receive your money, though you can sometimes pay a fee to get your funds faster. For instance, you can get instant access* of up to $750 to your paycheck in advance for a fee with Current (once you qualify) or get it within three business days for free.
Is EWA a loan?
EWA is different from a loan. Loans entail borrowing money and then paying it back over a set period of time and typically with added interest. With EWA, you’re receiving money you’ve already earned, but earlier than you would normally receive it. The funds you’ve already accessed via EWA are then excluded from your paycheck as opposed to you having to pay them back.
What are the risks of using earned wage access?
While EWA can help you navigate the challenging situation of now having enough funds to cover your expenses, it’s important not to become reliant on the service. Remember that when you use EWA, you’re shrinking your next paycheck — and potentially tacking on a fee.
Does EWA affect your credit score?
No, EWA services typically don’t impact your credit score because you’re not taking out a loan. There is no hard credit check.
*Expedited disbursement of your Paycheck Advance is an optional feature that is subject to an Instant Access Fee and may not be available to all users. Expedited disbursements may take up to an hour. For more information, please refer to Paycheck Advance Terms and Conditions.
Suggested Reading